🚀Pharmaceutical Contract Development & Manufacturing Organization (CDMO) Market Projected to Reach USD 451.80 Billion by 2034 at a CAGR of 6.49%
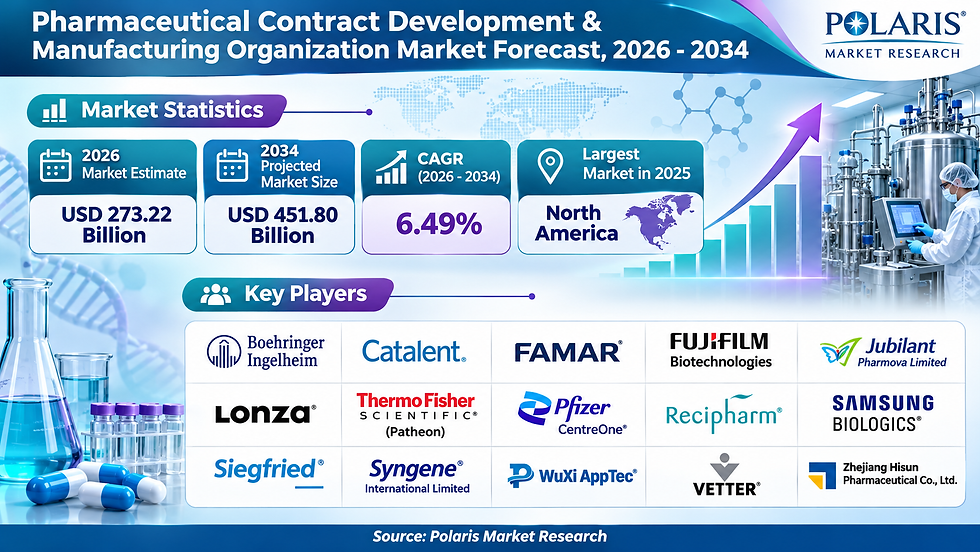
The global pharmaceutical contract development and manufacturing organization (CDMO) market is experiencing unprecedented transformation. Valued at USD 256.90 billion in 2025, the industry is projected to expand significantly, reaching USD 451.80 billion by 2034, driven by a steady compound annual growth rate (CAGR of 6.49%). Pharmaceutical and biotechnology enterprises increasingly rely on specialized CDMO partnerships to streamline drug development, optimize active pharmaceutical ingredient (API) synthesis, and manage complex regulatory landscapes without heavy capital investments in proprietary infrastructure.
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Key Market Growth Drivers
📈 Rising R&D Expenditure to Expand Product Pipelines: Increased investments in drug discovery by major players such as Merck’s USD 15.8 billion R&D allocation in 2025 fuel continuous demand for outsourced formulation, analytical testing, and clinical manufacturing.
🩺 Increasing Burden of Chronic Diseases: The surging global prevalence of cancer, cardiovascular conditions, diabetes, and respiratory disorders requires rapid, large-scale manufacturing of life-saving therapeutics.
🧬 Surging Demand for Biologics and Advanced Therapies: Complex biological drugs, biosimilars, monoclonal antibodies, and cell and gene therapies demand advanced cleanroom environments and specialized aseptic processing.
Key Market Dynamics
🏭 Strategic Outsourcing and Capacity Expansion: Companies like Lonza achieved 21.7% sales growth at constant exchange rates in 2025, heavily propelled by demand for their dedicated contract development and manufacturing services.
🌍 Geographic Shifts and Supply Chain Realignment: Heightened attention on supply chain resilience, risk mitigation regarding China CDMO sourcing, and regional legislation such as the BIOSECURE Act (signed in December 2025) prompt companies to diversify manufacturing partnerships.
🤖 Technological Integration: The widespread adoption of continuous pharmaceutical manufacturing, single-use bioprocessing components, and artificial intelligence-driven quality analytics optimizes production efficiency and minimizes batch contamination.
Market Challenges and Opportunities
⚠️ High Infrastructure and Capital Costs: Constructing specialized GMP-compliant facilities and maintaining stringent data integrity standards demand extensive upfront capital.
🚧 Supply Chain Bottlenecks: Delays in facility expansions or heavy reliance on single-source raw material suppliers can disrupt clinical and commercial supply continuity.
💡 Lucrative Outsourcing Opportunities: Emerging biotech startups and mid-sized pharmaceutical innovators present lucrative avenues for end-to-end CDMO partners capable of providing integrated services from early discovery to commercial packaging.
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Market Segmentation
By Type: Divided into Small Molecules (capturing 64.20% of market revenue in 2025 due to widespread generic formulations) and Large Molecules (projected to surge at a 7.47% CAGR through 2034).
By Product: Segmented into Active Pharmaceutical Ingredients (APIs), which represented 58.40% of 2025 revenue, and Drug Products (projected at a 7.12% CAGR).
By Service: Dominated by Contract Manufacturing, accounting for 66.40% of market share in 2025, alongside contract development, packaging, and regulatory affairs.
By Workflow: Comprising clinical manufacturing and Commercial Manufacturing, the latter leading with 68.75% of revenue in 2025.
By Therapeutic Area: Led by Oncology at 32.15% of revenue, followed by infectious diseases, neurological disorders, and cardiovascular conditions.
By End Use: Segmented across small, medium, and Large Pharmaceutical Companies, with major enterprises holding 68.40% of the market share.
Regional Landscape: North America spearheaded global demand, representing 34.60% of market revenue in 2025, while Asia Pacific stands out as the fastest-growing region, forecasted at a 7.18% CAGR driven by expansions in India and China.
Market Key Companies
Leading international players driving end-to-end innovation and strategic acquisitions within the sector include:
Lonza
Catalent
Boehringer Ingelheim
Thermo Fisher Scientific (Patheon)
Samsung Biologics
FUJIFILM Biotechnologies
WuXi AppTec
Vetter
Recipharm
Siegfried
Syngene International Limited
Jubilant Pharmova Limited
Pfizer CentreOne
FAMAR
Zhejiang Hisun Pharmaceutical Co., Ltd.
Market Trends
Continuous Manufacturing Innovation: Adoption of continuous processing techniques supported by regulatory frameworks like the FDA's ICH Q13 guidance.
Advanced Fill-Finish Automation: Scaling up sterile injectable capabilities through strategic acquisitions, such as Thermo Fisher Scientific's integration of Sanofi’s New Jersey facility.
Strategic Consolidation: Major corporate maneuvers, including Novo Holdings' acquisition of Catalent and Samsung Biologics' proposed investments, underline a strong trend toward consolidated global biologics and peptide supply networks.
Future Outlook
The pharmaceutical CDMO sector is primed for sustained expansion through 2034. As biotechnology innovators continue to prioritize asset-light operational models, CDMOs offering flexible capacity, rigorous regulatory compliance, and cutting-edge continuous manufacturing technologies will remain central to the global healthcare supply chain. Long-term success will rely on robust risk management, agile geographic diversification, and unwavering adherence to stringent quality standards.


Comments