🌡️ Global Heat Exchangers Market Size Valued at USD 19.92 Billion in 2025 and Projected to Exhibit a CAGR of 6.9% From 2026 to 2034 📈
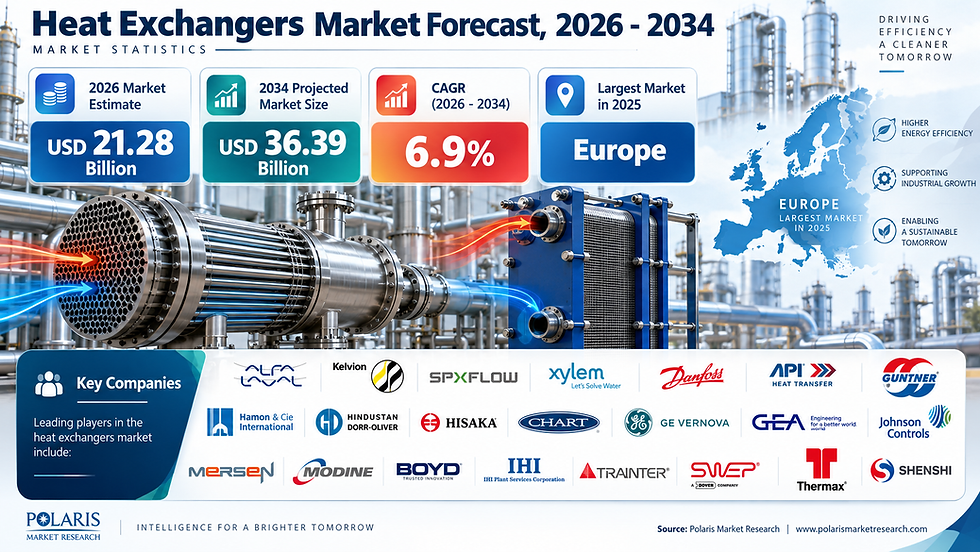
The global heat exchangers market stands as an indispensable pillar of modern industrial operations, thermal management, energy conservation, and efficient fluid processing. As industries across the globe accelerate their transition toward optimized operational efficiency, lower carbon footprints, and strict environmental compliance, advanced thermal transfer systems have grown fundamentally vital. Comprehensive market evaluations by Polaris Market Research indicate that the global heat exchangers market size was valued at USD 19.92 billion in 2025 and is projected to expand robustly to reach USD 36.39 billion by 2034, reflecting a compound annual growth rate (CAGR of 6.9% from 2026 to 2034).
This extensive market expansion is propelled by relentless industrialization, rapid urbanization, and a unified global commitment to thermal sustainability. Operating on core thermodynamic principles, heat exchangers facilitate the efficient transfer of thermal energy between two or more fluids separated by solid walls of high thermal conductivity without allowing the fluids to mix directly. Their widespread deployment across chemical processing plants, petrochemical refineries, power generation stations, HVAC installations, and cryogenic engineering underscores their immense economic and ecological importance.
Market Overview 🌍
The global heat exchangers landscape encompasses diverse configurations designed to fulfill strict thermal and mechanical criteria. Operating with a 2026 market estimate of USD 21.28 billion and pacing toward a projected 2034 valuation of USD 36.39 billion, the industry is shaped by continuous engineering advancements and rigorous regulatory mandates. In 2025, Europe emerged as the largest regional market, supported by extensive public and private funding and strict refrigerant efficiency standards, while Asia Pacific closely followed, dominating with a 31.9% market share driven by heavy manufacturing and petrochemical activities.
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Key Market Growth Drivers ⚙️
The rapid trajectory of the heat exchangers industry is fueled by a combination of regulatory frameworks, environmental imperatives, and technological breakthroughs. Key growth drivers include:
Rising Government Support and Initiatives: Regulatory agencies worldwide enforced by frameworks such as the Paris Agreement, the U.S. Department of Energy (DOE) efficiency mandates, and National Energy Commissions enforce stringent energy-efficiency standards. These norms mandate smart construction and manufacturing practices, accelerating the adoption of energy-efficient heat exchange units.
Growing Demand for Heat Pumps: Heat exchangers serve as the vital thermal core of heat pump systems, regulating refrigerant charge, stability, performance, and equipment longevity. The surging residential and commercial deployment of eco-friendly heat pumps especially across Europe directly stimulates component demand.
Rising Data Center & AI/HPC Cooling Demand: The exponential proliferation of hyperscale data centers, cloud computing infrastructure, and artificial intelligence (AI) / high-performance computing (HPC) nodes generates immense thermal loads. According to the Indian Ministry of Electronics & IT, data center capacity in India alone reached 1500 MW as of 2025. Advanced liquid-to-air and liquid-to-liquid heat exchangers are fundamentally required to dissipate this heat and ensure equipment stability.
Growing Adoption of Printed Circuit & Compact Heat Exchangers: Industries operating under extreme pressures and demanding thermal environments increasingly favor printed circuit and compact heat exchangers. Their high power density, compact footprints, and superior structural durability make them ideal for modern space-constrained industrial setups.
Key Market Dynamics 🔄
The structural evolution of the thermal transfer ecosystem is dictated by evolving macroeconomic forces, material science innovations, and shifting supply chain paradigms. Key market dynamics encompass:
Escalating Industrial Decarbonization Initiatives: Industrial operators are actively retrofitting legacy infrastructure with next-generation, low-energy consumption heat exchangers to systematically curtail greenhouse gas emissions and optimize enterprise energy footprints.
Technological Integration of Advanced Materials: Manufacturers are heavily investing in corrosion-resistant superalloys, titanium matrices, and specialized composites to withstand aggressive chemical environments, high temperatures, and severe pressure differentials.
Fluctuations in Raw Material Pricing: The industry remains sensitive to volatile commodity prices involving essential core metals such as stainless steel, copper, and aluminum, requiring manufacturers to adopt agile supply chain and hedging strategies.
Regional Manufacturing Shifts: Rapid economic development, extensive plant construction, and heavy industrialization across emerging economies continue to redistribute manufacturing hubs and supply channels globally.
Market Challenges and Opportunities ⚖️
Navigating the competitive landscape requires industry stakeholders to proactively address persistent hurdles while capitalizing on emerging commercial avenues.
Market Challenges
Raw Material Price Volatility: Unpredictable cost swings in stainless steel, copper, and aluminum directly compress manufacturer profit margins and complicate long-term project budgeting.
High Initial Capital Expenditures: The integration of specialized, high-capacity, or custom-engineered alloy heat exchangers involves substantial upfront capital investment, which can deter smaller industrial enterprises.
Complex Maintenance and Fouling Issues: Scale formation, biological fouling, and chemical corrosion over prolonged operational cycles require rigorous cleaning regimens and scheduled downtime.
Market Opportunities
High-Efficiency Renewable Energy Applications: Expanding deployment within geothermal energy harvesting, hydrogen fuel cell systems, and green energy production offers lucrative avenues for specialized heat exchanger designs.
Cost-Effective Sustainable Innovations: Developing affordable, low-maintenance, and eco-friendly thermal transfer units tailored for small-to-medium enterprises unlocks massive untapped commercial demand.
Emerging Regional Markets: Rapid industrial expansion across developing economies in Asia-Pacific, Latin America, and the Middle East presents fertile ground for localized distribution and manufacturing partnerships.
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Market Segmentation 📊
The global heat exchangers market exhibits deep segmentation across product types, materials, end-use verticals, and geographical regions, reflecting diverse operational requirements.
By Product Type
Shell & Tube Heat Exchanger: Dominating the market with the largest share of 32.8% in 2025, renowned for handling high-pressure applications and severe industrial duties.
Plate & Frame Heat Exchanger: Witnessing significant growth at a 7.4% CAGR, valued for high thermal transfer efficiency, compact design, and modular maintenance flexibility.
Air-Cooled Heat Exchanger: Projected to grow at a 7.1% CAGR, driven by decreasing freshwater consumption in industrial processes and wide utility in water-scarce regions.
Cooling Towers: Anticipated to expand at a 6.6% CAGR, supported by the rising need for closed-loop cooling systems in power plants, manufacturing facilities, and data centers.
By Material Type
Stainless Steel: Accounting for the largest market size of 41.2% in 2025, driven by exceptional corrosion resistance, durability, and resilience in extreme physical conditions across food processing, chemical, and pharmaceutical sectors.
Carbon Steel: Projected to grow at a 6.5% CAGR, favored for its low cost, high strength, and ductility in less strenuous large-scale industrial environments.
Nickel Alloys: Expected to witness the fastest growth at a 7.8% CAGR, driven by extreme temperature resilience and superior performance in highly corrosive chemical and oil and gas processing environments.
By End-Use Industry
Chemical & Petrochemical: Leading the revenue share at 22.1% in 2025, driven by extensive temperature regulation, waste heat recovery, and fluid energy conveyance needs.
Oil & Gas: Projected to grow at a 7.2% CAGR, supported by continuous investments in oil refining, gas processing, and liquid natural gas infrastructure.
HVAC & Refrigeration: Anticipated to expand at a 7.3% CAGR, propelled by building decarbonization, rising construction activity, and the surge in heat-pump adoption.
Food & Beverage: Expected to grow at a 6.8% CAGR, driven by stringent hygiene standards and precise pasteurization and sterilization requirements.
Power Generation: Projected to grow at a 6.5% CAGR, fueled by global electricity demand and plant efficiency optimization.
Automobile: Anticipated to exhibit robust growth at a 7.5% CAGR, driven by automotive production and thermal management needs in electric and hybrid vehicles.
Pharmaceuticals: Expected to record the highest end-use growth at a 7.9% CAGR, driven by sterile process temperature control in drug compounding and manufacturing.
By Regional Analysis
Asia Pacific: Dominated the global market in 2025 with a 31.9% share, powered by extensive manufacturing hubs, chemical complexes, and booming infrastructure in China, Japan, and India. China is projected to grow at a 7.8% CAGR, while India leads regional growth at an 8.1% CAGR.
Europe: Held the position of the largest market in 2025 and is expected to grow significantly with a CAGR of 6.7%, fueled by robust public and private sector funding, energy-saving initiatives, and strict refrigerant standards in Germany, France, and the UK.
North America: Projected to grow at a 6.5% CAGR (with the US at 6.6% CAGR and Canada at 5.8% CAGR), characterized by advanced data center build-outs, stringent environmental standards, and modern industrial automation.
Middle East & Africa: Expected to witness growth at a 5.9% CAGR (Saudi Arabia at 6.3% CAGR, UAE at 6.5% CAGR), driven by oil and gas, petrochemical, and water treatment infrastructure investments.
Latin America: Anticipated to grow at a 6.2% CAGR (Brazil at 6.5% CAGR, Argentina at 5.8% CAGR), supported by mining, power generation, and energy facility expansions.
Market Key Companies 🏢
The global heat exchangers market features intense competition among established engineering giants and specialized thermal equipment manufacturers spearheading technological innovation. Key industry players include:
Alfa Laval
API Heat Transfer Inc.
Danfoss A/S
Exchanger Industries Corporation
GEA Group Aktiengesellschaft
Guntner GmbH
Hamon & Cie International
Hindustan Dorr-Oliver Ltd.
Hisaka Works, Ltd.
Chart Industries
GE Vernova
Johnson Controls
Kelvion Holding GmbH
Mersen
Modine Manufacturing Company
Boyd
IHI Plant Services Corporation
Tranter, Inc.
SWEP International AB
Thermax Limited
Shenshi
SPX FLOW, Inc.
Xylem Inc.
Market Trends 📈
Proliferation of Microchannel Heat Exchangers: Growing preference for microchannel designs that offer exceptional heat transfer coefficients with minimal refrigerant or fluid charges.
Digitalization and Smart Monitoring: Integration of IoT sensors and predictive maintenance algorithms to monitor fouling, pressure drops, and thermal efficiency in real time.
Green Refrigerant Compatibility: Designing systems optimized for eco-friendly, low Global Warming Potential (GWP) refrigerants in compliance with international environmental protocols.
Future Outlook 🔮
Looking toward 2034, the global heat exchangers market is primed for sustained, high-value expansion. Driven by the projected ascent to USD 36.39 billion at a steady 6.9% CAGR, the industry will increasingly prioritize modular manufacturing, advanced material sciences, and digital thermal optimization. As data centers, renewable energy grids, and chemical processing complexes scale globally, heat exchangers will remain foundational to global industrial sustainability and engineering excellence.

Comments