Transforming Precision Surgery: The Orthopedic Surgical Robots Market Projected to Reach USD 8.71 Billion by 2034 at a 16.8% CAGR 🚀🤖
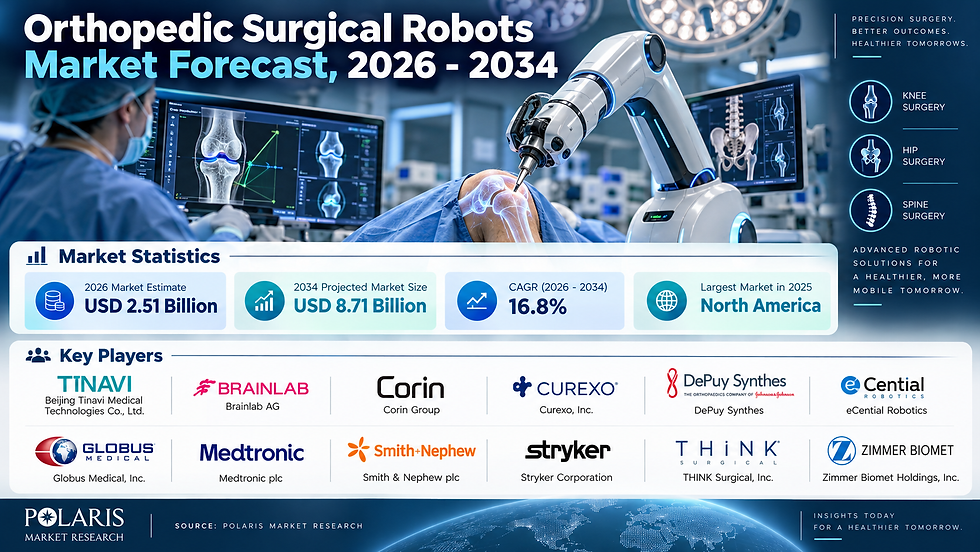
The convergence of artificial intelligence, advanced navigation tools, and robotic engineering is fundamentally redefining the landscape of modern healthcare. 🏥✨ According to comprehensive industry data, the orthopedic surgical robots market is experiencing unprecedented expansion, valued at USD 2.51 billion in 2026 and projected to surge to USD 8.71 billion by 2034, expanding at a robust compound annual growth rate (CAGR of 16.8%). 📈💡
As healthcare systems worldwide face mounting patient volumes and heightened expectations for surgical excellence, robotic-assisted technology has transitioned from a futuristic novelty into an indispensable standard of care. 🌐🌟
Market Overview 🌐📊
The global medical device sector is undergoing a profound paradigm shift towards digital integration and minimally invasive interventions. Within this transformation, orthopedic procedures particularly joint replacements demand ultra-precise bone preparation and implant placement to maximize longevity and minimize patient trauma. 🦴⚙️
In 2025, North America held the largest orthopedic surgical robots market share of 38.6%, underpinned by sophisticated healthcare infrastructure, high adoption rates of advanced medical technology, and favorable reimbursement frameworks. Meanwhile, the Asia Pacific region is anticipated to record the fastest growth, expanding at a remarkable 18.9% CAGR, propelled by progressive government initiatives, expanding healthcare expenditures, and a rapidly aging demographic base. 🌏🏥
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Key Market Growth Drivers 🚀📈
Rising Volume of Joint Replacement Procedures: The relentless aging of the global population has led to a steep escalation in musculoskeletal disorders such as osteoarthritis. This demographic shift drives unprecedented demand for knee and hip replacements, compelling surgeons to utilize robotic systems for enhanced precision, optimal implant alignment, and superior long-term clinical outcomes. 🦿👴
Technological Innovations in Robotics and Navigation: Modern robotic iterations integrate cutting-edge software and navigation systems that provide surgeons with real-time intraoperative data. Recent technological milestones such as Stryker’s July 2026 rollout of the Mako RPS system for total knee replacements and DePuy Synthes's June 2026 commercialization of VELYS Hip Navigation with AI Assistance demonstrate how automated image analysis and landmark recognition are accelerating market uptake. 💻🔬
Expansion of Ambulatory and Specialty Settings: Healthcare delivery is decentralizing rapidly. Specialty orthopedic clinics and ambulatory surgical centers are increasingly procuring compact, high-efficiency robotic platforms to deliver patient-centric, cost-effective outpatient joint procedures. 🏢💡
Key Market Dynamics 🔄⚙️
Intraoperative Precision and Reduced Variability: Traditional manual techniques are inherently susceptible to human variability. Robotic platforms empower surgeons by executing predefined surgical plans with sub-millimeter accuracy, significantly reducing revision rates and protecting critical soft tissues. 🎯🩺
Strategic Industry Acquisitions and Partnerships: Major medical technology leaders are aggressively acquiring proprietary tracking and navigation technologies such as DePuy Synthes's May 2026 agreement regarding Gemtrack tracking technology to fortify their robotic ecosystems and surgical intelligence portfolios. 🤝💼
Integration of Artificial Intelligence (AI): AI-driven software is increasingly utilized to automate pre-surgical planning, analyze complex medical images, and deliver bespoke, patient-specific anatomical data during active surgical workflows. 🤖🧠
Market Challenges and Opportunities ⚡🔍
High Capital Expenditure and Equipment Costs: The substantial upfront investment required to purchase, maintain, and service sophisticated robotic systems can restrict adoption among smaller community hospitals and resource-constrained clinics. 💰⚠️
Steep Learning Curves and Training Requirements: Operating advanced surgical robotics demands specialized, rigorous training for orthopedic surgeons and surgical support teams, temporarily impacting operating room throughput during the initial adoption phase. 🎓⏱️
Untapped Emerging Markets: Developing economies across Latin America, Asia Pacific, and the Middle East present lucrative expansion avenues. As healthcare budgets increase and medical tourism flourishes, these regions offer immense potential for market penetration. 🌍✨
🌐𝐁𝐫𝐨𝐰𝐬𝐞 𝐅𝐮𝐥𝐥 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬:
Market Key Companies 🏢🏆
The competitive landscape of the orthopedic surgical robots market is characterized by intense strategic innovation, regulatory clearances, and global portfolio expansions led by top-tier medical device manufacturers:
Stryker Corporation
Zimmer Biomet
Smith & Nephew
Medtronic
Globus Medical
THINK Surgical, Inc.
Renishaw plc
Auris Health Inc.
Asensus Surgical, Inc. (Transenterix)
Medrobotics Corporation
Market Segmentation 🧩📋
The market is meticulously categorized to address diverse clinical needs across global healthcare ecosystems:
By Application: Dominated by the knee segment, which secured a 46.8% share in 2025 driven by high osteoarthritis prevalence, alongside rapidly expanding spine and hip segments. 🦿🦴
By Component: Led by the robotic systems segment, accounting for 62.4% of the market share in 2025, as integrated hardware platforms form the vital core infrastructure for high-volume joint arthroplasties. ⚙️💻
By End-User: Comprising hospitals, specialty orthopedic clinics, and ambulatory surgery centers (ASCs), with specialty orthopedic clinics projected to grow at a stellar 18.2% CAGR. 🏥🏢
Market Trends 📊🔮
Shift Toward Open Architecture and Handheld Integration: Manufacturers are moving beyond bulky, closed systems by introducing hybrid platforms such as handheld robotic instruments and modular software upgrades that seamlessly integrate into existing hospital operating rooms. 🛠️🔄
Enhanced Data Analytics and Tele-Mentoring: Modern robotic platforms generate vast quantities of surgical data, enabling continuous quality improvement, outcome tracking, and remote expert proctoring across global medical networks. 📈🌐
Future Outlook 🌟🔭
Looking ahead to 2034, the orthopedic surgical robots market is poised for transformative, sustained growth. As artificial intelligence deepens its integration into surgical workflows, hardware becomes more ergonomic, and outpatient adoption accelerates, robotic assistance will transition from an elite premium offering to the universal standard of orthopedic care. 🚀🏥 For healthcare executives, investors, and clinical leaders, embracing these advanced technologies is essential for driving clinical excellence, enhancing patient satisfaction, and securing competitive advantage in the future of medicine. 💼✨

Comments